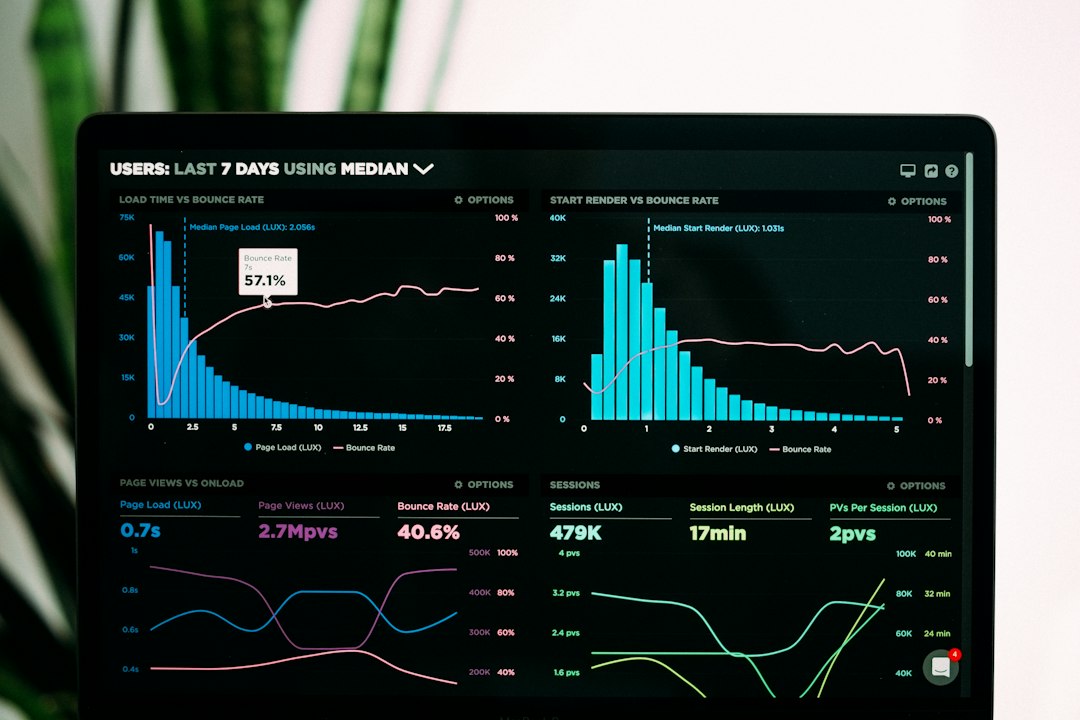
Understanding the discrepancy between Backtesting vs. Real-Time Performance: Insights from Kevin J. Davey is a critical step for any systematic trader. While backtesting provides a historical map, real-time execution often presents unforeseen hurdles such as slippage, latency, and psychological stress. As explored in The Ultimate Guide to Building Winning Algorithmic Trading Systems: Insights from Kevin J. Davey, the goal of a robust developer is not just to find a profitable curve, but to build a system that survives the transition to live markets. Kevin Davey emphasizes that a backtest is merely a proof of concept, while incubation is the true test of a strategy’s viability.
Validate your strategy with instant backtesting
Backtest LibraryThe Reality Gap: Why Backtests and Live Results Diverge
The “Performance Gap” is the difference between the theoretical results shown in a strategy tester and the actual equity curve in a live brokerage account. Kevin Davey identifies several primary culprits for this divergence:
- Slippage and Commissions: Many traders underestimate the cost of doing business. In a backtest, you might get filled at the “last price,” but in reality, you pay the spread.
- Data Mining Bias: If you test 10,000 variations of a strategy, one is bound to look like a “Holy Grail” purely by chance. This is why The Dangers of Over-Optimization are so prevalent in failed systems.
- Look-Ahead Bias: Accidentally using future information (like today’s closing price to calculate today’s entry) creates impossible historical returns.
To combat these issues, Davey advocates for a disciplined approach to Kevin J. Davey’s 5-Step Framework for Professional Strategy Development, which prioritizes validation over optimization.
Practical Advice: Bridging the Performance Gap
Kevin Davey’s methodology involves several actionable steps to ensure your live trading matches your expectations:
- The Incubation Period: Never go from backtest to full-size live trading. Davey suggests “incubating” a strategy—trading it in a demo account or with minimum lot sizes for 3 to 6 months—to ensure it tracks its backtested logic.
- Comparing Walk-Forward to Live Data: By Mastering Walk-Forward Analysis, you create a “blind” out-of-sample period that simulates real trading. If the live results are significantly worse than the walk-forward results, the system is likely broken.
- Stress Testing with Monte Carlo: Use statistical simulations to understand the range of possible outcomes. Using Monte Carlo Analysis to Predict and Manage Trading Drawdowns helps traders stay calm when the real-time equity curve dips, provided it stays within the simulated parameters.
Case Studies: Lessons from the Real World
Case Study 1: The Scalping Mirage
A trader developed a high-frequency futures system with a backtested profit factor of 2.5. However, the system relied on capturing 1-2 ticks per trade. In real-time execution, the slippage and exchange fees exceeded the average profit per trade. By applying Developing Robust Algorithmic Systems Specifically for Futures Markets, the trader realized the system was mathematically unviable in a live environment despite the “perfect” backtest.
Case Study 2: The “Over-Fitted” Breakout System
A participant in one of Davey’s workshops created a breakout system that performed flawlessly from 2018 to 2022. When put into incubation, the system failed immediately. The trader had used too many filters, effectively “solving” the past market noise. Following the advice on How to Identify and Filter Low-Quality Trading Signals, they simplified the logic, which led to more modest—but consistent—real-time performance.
Managing Expectations and Psychology
Even with a perfect technical setup, the Systematic Trading Psychology of Kevin J. Davey plays a massive role. When a backtest shows a 20% drawdown, it happens in seconds on a screen. In real-time, that drawdown might last three months. Without proper Position Sizing Strategies, most traders will abandon a winning system during a natural performance lull. Davey’s own journey, detailed in The Evolution of a World Cup Trading Champion, proves that success comes from trusting the process over the immediate P&L.
Conclusion
Navigating the transition of Backtesting vs. Real-Time Performance: Insights from Kevin J. Davey requires more than just good code; it requires a rigorous validation process and a realistic understanding of market mechanics. By incorporating incubation, walk-forward analysis, and conservative slippage estimates, you can build systems that don’t just look good on paper but actually perform in the heat of the market. For a deeper dive into the entire system-building lifecycle, refer back to The Ultimate Guide to Building Winning Algorithmic Trading Systems: Insights from Kevin J. Davey.
Frequently Asked Questions
1. Why does my backtest look better than my live results?
This is usually due to “optimization bias” or failing to account for realistic slippage and commissions. Real-time markets involve execution delays and varying liquidity that standard backtests often ignore.
2. How long should I incubate a strategy before trading it live?
Kevin Davey typically recommends at least 3 to 6 months of incubation. This period allows you to see if the strategy’s live performance correlates with its walk-forward results before committing significant capital.
3. Can I use Monte Carlo analysis to fix a bad backtest?
No, Monte Carlo analysis is used to predict the range of future outcomes and drawdowns based on existing trade data. It is a tool for risk management, as explained in The Ultimate Guide to Building Winning Algorithmic Trading Systems, not a way to fix a broken strategy.
4. What is the most common mistake in transitioning to real-time trading?
Over-leveraging too early. Traders often see a backtest with a high Sharpe ratio and assume the risk is low, but they fail to account for the psychological pressure of real-money drawdowns.
5. How does slippage impact different types of strategies?
Slippage has a massive impact on high-frequency or small-target strategies. If your average trade profit is small, a single tick of slippage can turn a winning system into a losing one.
6. Is walk-forward analysis better than a standard backtest?
Yes, because walk-forward analysis tests the strategy on data it has never seen before in a sequential manner, which more closely mimics real-time performance and helps detect curve-fitting.
7. How do I know when to stop trading a system that is underperforming?
You should establish “fail points” based on your backtest and Monte Carlo simulations. If the real-time drawdown exceeds the historical maximum drawdown by a certain percentage, it is time to re-evaluate the system.